[Civil Appeal No: A-02(NCC)(A)-1391-07-2025]
28 September 2026
JUDGMENT
A. Introduction
[1] This judgment discusses the main question of whether a company and its directors can insist that an executor of an estate of a deceased shareholder of the company (Deceased) "transfer", instead of "transmit", the shares of the Deceased to the beneficiaries named in the Deceased's will (Beneficiaries). A "transfer" of the Deceased's shares to the Beneficiaries attracts stamp duty under the Stamp Act 1949, while stamp duty is not imposed on a "transmission" of the Deceased's shares to the Beneficiaries.
B. Background
[2] Madam Wong Kim (Testatrix) owned 986,606 shares (Testatrix's Shares) in the 1st respondent company (1st Respondent).
[3] The 2nd to 7th respondents ("2nd Respondent" to "7th Respondent") are the directors of the 1st Respondent. This judgment shall refer to the 1st to 7th Respondents collectively as the "Respondents".
[4] The Testatrix executed a will dated 15 December 2010 (Will).
[5] On 19 February 2015, the Testatrix died.
[6] The Will stated as follows, among others:
(1) Mr. Loh Koh Fah (Executor), the eldest son of the Testatrix, was named as the sole executor of the estate of the Testatrix (Estate); and
(2) the Executor shall, among others, divide and distribute all the assets of the Testatrix, including the Testatrix's Shares, to the following persons in the following proportions:
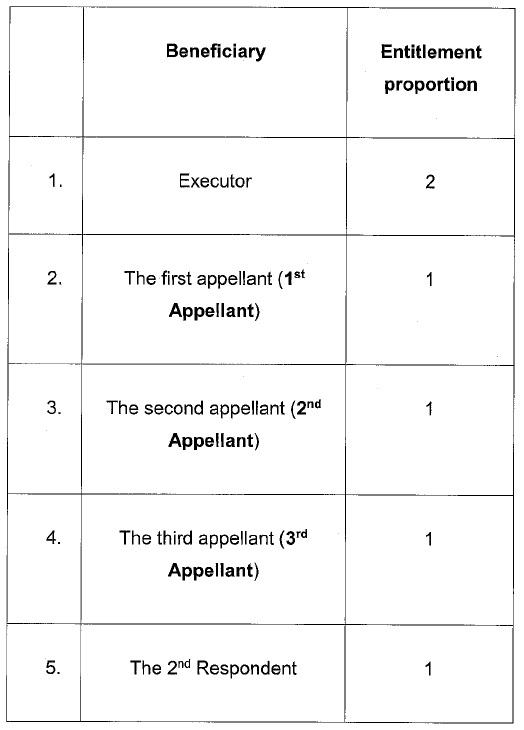
This judgment shall refer to the 1st to 3rd Appellants collectively as the "Appellants".
[7] The Executor had obtained a probate of the Will from the High Court (Probate).
[8] All the Testatrix's Shares were transmitted to the Executor [Transmission (Testatrix-Executor)] and registered on the 1st Respondent's register of members (1st Respondent's Register).